
Asset Finance Case Study: 5 Ways Australian SMEs Use Asset Finance to Grow
Asset finance helps Australian SMEs acquire equipment, machinery and technology without paying the full cost upfront. For many growing businesses, that means preserving working capital, improving productivity and funding essential assets in a more strategic way.
In practice, asset finance is commonly used by businesses that want to:
acquire equipment without a large upfront cash outlay
preserve working capital for operations and growth
upgrade outdated machinery or technology
improve productivity and efficiency
respond quickly to new business opportunities
This case study article looks at five practical examples of how SMEs can use asset finance, across industries including construction, manufacturing, professional services, food production and logistics.
If you are an Australian business owner considering equipment finance, machinery finance or technology finance, these examples show how asset finance can support business growth in real-world scenarios.
What is asset finance?
Asset finance is a type of business funding used to acquire income-producing or operational business assets without requiring full payment upfront.
Businesses commonly use asset finance for:
For SME owners, asset finance is often used to help balance two competing priorities:
acquiring the assets needed to grow
preserving cash flow and capital flexibility
That is why asset finance for Australian SMEs is often an important funding tool for businesses that are expanding, upgrading or improving operational capability.
Asset Finance for Australian SMEs
Australian SMEs often use asset finance because it can help them secure business-critical assets while protecting cash reserves.
Common reasons businesses use asset finance
to avoid a major upfront capital expense
to preserve working capital
to improve productivity and efficiency
to replace outdated equipment or machinery
to support expansion
to better align funding with business use of the asset
For many businesses, the goal is not simply to buy an asset. It is to fund that asset in a way that supports broader commercial objectives.
5 Asset Finance Case Studies for Australian SMEs
Below are five mini case studies showing different ways a business can use asset finance.
1. Equipment finance for a civil contractor expanding capacity
Business type: Civil construction contractor
Asset financed: Excavator, skid steer and trailer package
Primary funding objective: Increase project capacity and reduce reliance on hired equipment
A growing civil contractor was winning more work, but its operational model was under pressure. The business relied heavily on hired machinery and subcontracted equipment to complete projects, which was affecting margins, scheduling and delivery control.
Hiring equipment solved the immediate need, but it created longer-term problems:
higher operating costs
reduced flexibility during busy periods
limited control over job scheduling
greater reliance on third-party availability
The contractor used equipment finance to fund a new machinery package rather than paying the full purchase cost upfront. This allowed the business to acquire essential assets while preserving capital for wages, fuel, insurance and tender-related costs.
Result
The business was better positioned to:
take on more projects
improve control over delivery timelines
reduce dependency on hired equipment
support stronger margin retention over time
This is a strong example of how equipment finance for construction businesses can support growth, improve delivery capability and reduce operational inefficiencies.
2. Machinery finance for a manufacturer upgrading production
Business type: Manufacturing business
Asset financed: Equipment and production line machinery
Primary funding objective: Improve output and reduce bottlenecks
A light manufacturing business had identified a clear growth issue: its production equipment was aging, maintenance costs were rising and bottlenecks were limiting throughput.
Management wanted to install newer machinery that would improve output and consistency. However, purchasing the equipment outright would have tied up capital that the business preferred to retain for inventory, labour and working capital.
By using machinery finance, the manufacturer was able to upgrade production equipment while spreading the cost over time.

Result
The upgraded equipment helped the business:
increase production efficiency
reduce downtime
lower maintenance-related disruption
support future revenue growth
This case study shows how machinery finance for manufacturers can be used to modernise operations, reduce inefficiencies and support business expansion.
3. Technology finance for a professional services firm scaling its team
Business type: Professional services firm
Asset financed: Laptops, servers, cybersecurity systems and office technology
Primary funding objective: Upgrade business systems while preserving cash flow
A professional services business was growing its headcount and needed to modernise its technology environment. Existing systems were becoming outdated, and the firm needed better laptops, stronger cybersecurity capability and improved infrastructure to support a larger team and hybrid work model.
While the business could have funded the upgrade from cash reserves, management preferred to avoid a significant upfront outlay.
Using technology finance, the firm was able to implement the required technology upgrades while maintaining stronger liquidity.
Result
The business was able to:
equip new staff properly
strengthen cybersecurity and data protection
support remote and hybrid work
avoid a major one-off technology spend
This is a practical example of technology finance for business growth, particularly for SMEs that rely on secure, current and scalable digital infrastructure.
4. Asset finance for a food producer investing in specialised equipment
Business type: Food production business
Asset financed: Packaging equipment and refrigeration systems
Primary funding objective: Increase production capability and pursue larger contracts
A food production business had the opportunity to service larger wholesale accounts, but doing so required additional packaging and refrigeration equipment.
The opportunity made commercial sense, but management wanted to avoid putting pressure on cash flow at a time when stock costs and working capital demands were already elevated.
By using asset finance, the business acquired the specialised equipment required to pursue growth without committing a large amount of capital upfront.
Result
The business was better placed to:
increase production capability
meet larger customer requirements
preserve cash for inventory and operations
support a growth phase more strategically
This case study highlights how asset finance for food businesses can help fund specialised equipment needed for scale, compliance and operational growth.
5. Equipment and technology finance for a logistics business improving warehouse operations
Business type: Logistics and warehousing operator
Asset financed: Forklifts, warehouse equipment and scanning technology
Primary funding objective: Support volume growth and warehouse efficiency
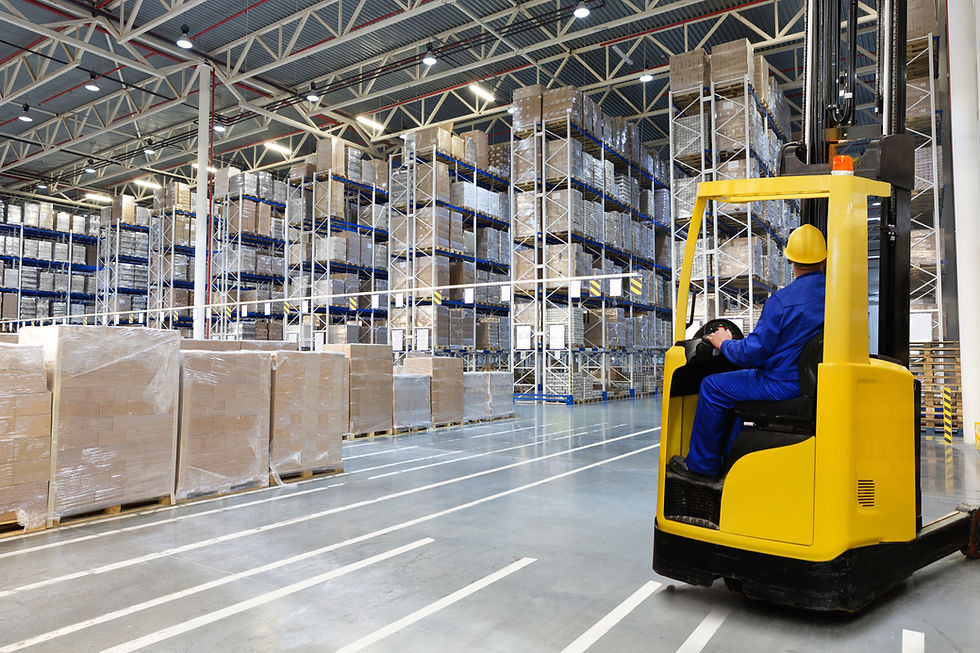
A logistics business was experiencing higher operational throughput and needed additional forklifts, handling equipment and scanning systems to maintain service levels and improve warehouse productivity.
The business had available capital, but management wanted to preserve liquidity for hiring, fuel, customer onboarding and other strategic priorities.
Through a tailored equipment finance and technology finance approach, the business was able to secure the assets needed for growth while retaining stronger balance sheet flexibility.
Result
The business improved its ability to:
manage higher activity volumes
improve warehouse efficiency
support service performance during growth
preserve capital for broader business needs
This is a useful example of how asset finance for logistics businesses can support operational scalability without unnecessarily tying up working capital.
Key lessons from these asset finance case studies
Across very different sectors, the same themes appear again and again.
Asset finance can help businesses:
preserve working capital
acquire essential equipment sooner
improve productivity
reduce operational constraints
support expansion
respond to commercial opportunities faster
In other words, asset finance is not just about funding an asset. It is about helping a business make smarter capital allocation decisions.
How to assess whether asset finance may suit your business
If you are considering asset finance, it helps to look beyond the purchase price alone.
Questions SME owners should ask
What business outcome will the asset improve?
Will it increase output, reduce downtime, improve service delivery, support staff, or unlock new work?
What is the cost of delaying the purchase?
Waiting may preserve cash in the short term, but it can also lead to missed revenue, lower efficiency or reduced competitiveness.
Is preserving working capital important right now?
For many businesses, the answer is yes. Keeping cash available for operations, payroll, stock or growth can be just as important as securing the asset itself.
Does the funding structure fit the commercial objective?
The right funding structure depends on the business, the asset and the broader strategy.
Why use a broker for asset finance?
The asset finance market is broad, and lender appetite can vary significantly depending on:
the asset type
the industry
the size and profile of the business
the commercial purpose of the funding
Working with an asset finance broker can help businesses assess a broader range of funding options and structure finance around their actual objectives.
Benefits of working with a broker
access to a broader lender panel
more tailored structuring options
guidance aligned to the commercial use of the asset
support navigating the funding process
At CapStack Asset Finance, we work with Australian SMEs looking to fund equipment, machinery and technology in a commercially sensible way.

Final thoughts on asset finance for Australian SMEs
For many SMEs, growth depends on having the right tools in place at the right time.
That may mean machinery for a contractor, production equipment for a manufacturer, upgraded systems for a service firm, or specialised technology for a logistics operator.
These case studies show that asset finance can be a practical and strategic tool for business growth. When structured correctly, it can help businesses invest in capability while preserving cash flow and flexibility.
If your business is planning to acquire equipment, machinery or technology, the right asset finance solution may help you move forward with greater confidence and less pressure on working capital.
Speak with a CapStack Asset Finance specialist
Planning to acquire equipment, machinery or technology for your business?
Speak with a CapStack Asset Finance specialist to discuss your options.
Frequently asked questions about asset finance
What is asset finance?
Asset finance is a type of business funding used to help a business acquire assets such as equipment, machinery, vehicles or technology without paying the full purchase price upfront.
What can asset finance be used for?
Asset finance can be used for a wide range of business assets, including equipment, machinery, technology, vehicles, fitout items and specialised operating assets.
Why do businesses use asset finance?
Businesses often use asset finance to preserve working capital, smooth cash flow, avoid a large upfront expense and fund assets in a more strategic way.
Is asset finance only for large businesses?
No. Asset finance is widely used by Australian SMEs across sectors including construction, manufacturing, logistics, food production and professional services.
Can asset finance be used for technology?
Yes. Technology finance can be used for business assets such as laptops, servers, software-related infrastructure, cybersecurity systems and office technology.
Can asset finance help with business growth?
Yes. Many businesses use asset finance to improve productivity, expand capacity, replace inefficient equipment or support growth opportunities.
Why use a broker for asset finance?
A broker can help assess lender options, compare structures and align the funding solution with the business’s commercial objectives.


Comments